Sky Vegas Deposit Declined in Ireland: What to Do
Direct answer: A declined deposit normally means the payment provider did not authorise it, but incorrect card details, an active deposit control, verification or an account block can also stop the transaction. Check the on-screen reason and provider before retrying.
Verified snapshot
Deposit, withdrawal and account facts
| Normal provider decline | The provider denied permission to take funds |
|---|---|
| Multiple transactions | Can trigger manual authorisation |
| Incorrect card details | Can prevent card addition or deposit |
| Third-party method | Not permitted |
| Deposit control | Can stop a deposit even when the provider would approve it |
| Blocked deposits | Sky may restrict deposits after attempted contact or recent account activity |
| Withdrawal | Can remain available separately |
The live Irish EUR cashier is the final check for account-specific limits and availability. This page does not convert UK values or guess unpublished euro figures.
Step by step
How to complete the payment route
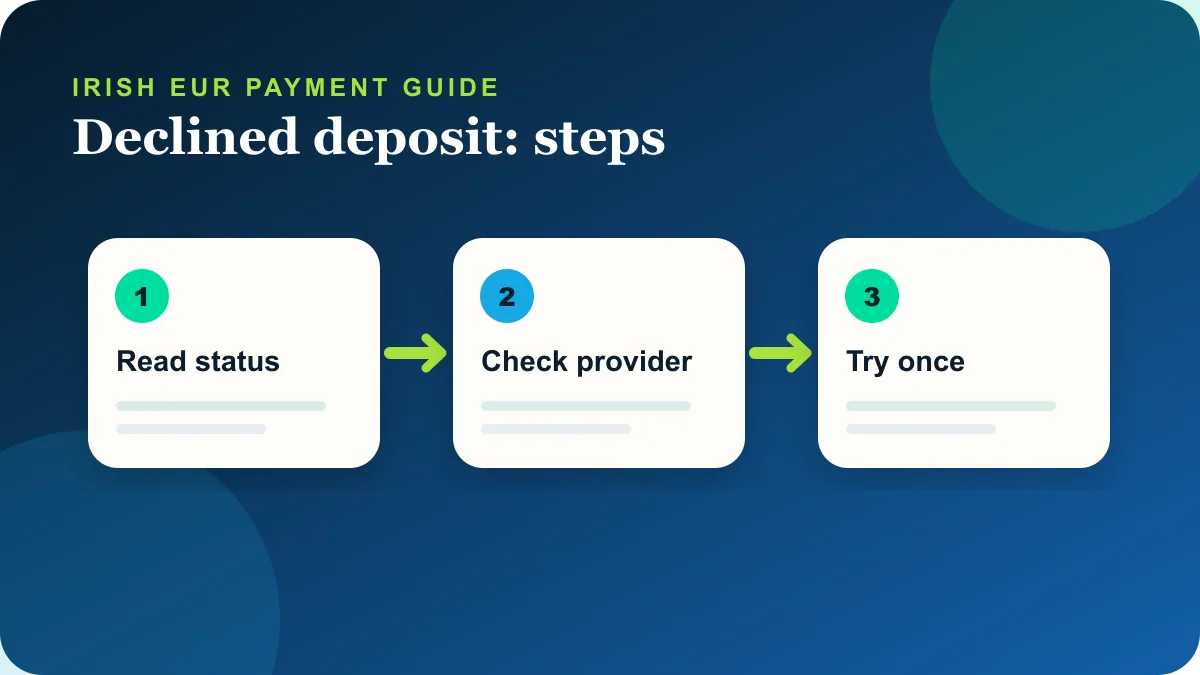
- 1Read the exact decline message
- 2Check My Transactions for a pending or duplicate entry
- 3Confirm the method belongs to the Sky account holder
- 4Check card details, expiry or bank authentication
- 5Review Deposit Controls and any verification notice
- 6Contact the payment provider or Sky route named by the message
Payment check 01
What a decline actually means
A decline is a status, not proof that the payment method is permanently unsupported. The next step depends on whether the refusal came from the bank, wallet, Sky account or a control. The useful decision is therefore not whether the method exists in the abstract, but whether the Irish EUR cashier presents the exact route and status described here.
Sky’s deposit help says the provider denies permission in a standard decline and may refer repeated online transactions for manual authorisation. This public evidence sets a baseline, while the signed-in screen supplies the account-specific minimum, maximum and availability. The page deliberately avoids converting sterling examples into invented euro limits.
This page is for a customer who pressed Deposit and received a decline rather than a pending or successful result. Read the status first, then choose the next action once. Multiple rapid attempts can create duplicate pending entries or prompt a provider review without resolving the original cause.
Payment check 02
Match the symptom to the responsible party
Provider refusal, wrong card data, a company or third-party card, multiple rapid attempts and account controls each have distinct remedies. Start by separating a provider refusal, an account restriction and a payment that has been authorised but not yet reflected. Those states look similar to the customer but require different actions.
Do not raise the amount or rotate through other people’s cards to test the system. Repeating the same payment before checking its status can make the transaction history harder to read. Use My Transactions, the bank or wallet record and the on-screen message together.
The troubleshooting table pairs each common symptom with a specific next step. It is not a substitute for the account message. If the message names verification, a safer-gambling control or a particular method, follow that route rather than choosing a generic support category.
Payment check 03
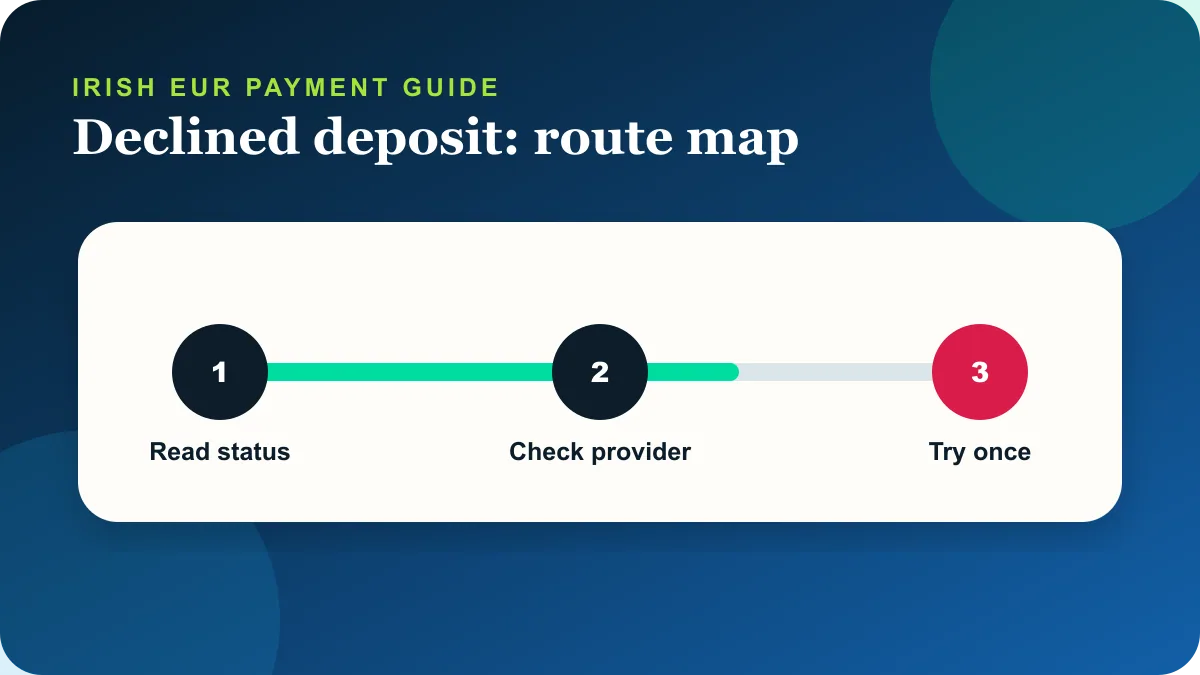
Run one controlled deposit check
Return to the method screen, verify ownership and details, then compare the attempt with the provider record and the active account limit. The route begins in My Account, then Payments, then Deposit. A stored method must still be current, owned by the account holder and accepted for the EUR account.
One corrected retry can be reasonable after the cause is understood; repeated blind attempts are not. Each step below represents one interface action rather than a promise about the provider’s result. The final confirmation screen is the point at which the account reports success, failure or a pending state.
Before confirming, compare the amount with the personal deposit control visible in the account. A lower account control takes precedence over a payment-provider limit. If a method is unavailable, do not work around the restriction with another person’s payment details.
Payment check 04
Verification before another attempt
If the account requests verification or payment ownership evidence, complete that task before another attempt. Irish proof-of-address review can require two accepted documents showing the full name and address. The operator lists a driving licence, a recent utility bill, a recent state letter, a recent insurance letter and a recent bank statement, subject to its upload rules.
Photo ID should be current and readable. Sky lists passports, driving licences, passport cards and national ID or residence permits; it says an Irish Age Card is not accepted for this purpose. Proof of address must be separate from the document used as proof of identity.
Document review is easiest to prepare before a time-sensitive withdrawal. File type, colour, date and matching personal details matter more than decorative scanning. Use the secure Document Uploader or the support route named by the operator, never an unverified email address found on a comparison page.
Payment check 05
Withdrawals remain a separate path
A deposit decline does not automatically stop an available withdrawal, and Sky says withdrawals can still be made when deposits are blocked. A withdrawal option can depend on a previous deposit, the Net Deposits position and whether the receiving card or bank supports the relevant payment rail.
Use the Withdraw section separately and follow its permitted method and verification status. The confirmation supplied after submission is more useful than a generic average because it identifies the selected route. Preserve that confirmation and allow the published window to pass before treating the transaction as missing.
If the original method cannot receive withdrawals, the operator points customers toward Pay by Bank where available. That alternative still has to appear in the account and may require an initial association or deposit before it becomes usable.
Payment check 06
Compare decline points by method
Pay by Bank, debit card and Apple Pay can fail at different authentication points, so the visible method name matters. The comparison is limited to routes publicly named by Sky for deposits or withdrawals; removed methods such as PayPal and Google Pay are not presented as current alternatives.
Speed alone is not enough. Debit card and Apple Pay can be relevant to a deposit-led promotion, while Pay by Bank has its own Irish timing and eligibility rules. The best route is the one that is present, owned by the customer, compatible with the intended withdrawal and understood before confirmation.
Switch methods only when the cashier presents an approved alternative and the original status is settled. If an alternative is genuinely faster for the scenario, the table says so. A faster published rail does not bypass verification, Net Deposits or an account control.
Payment check 07
Build a support-ready decline record
Capture the decline wording, timestamp and last four card digits or bank route without sensitive credentials. Record only what is needed to trace the transaction. A screenshot of the status and a transaction reference are more useful than a screenshot containing full payment credentials.
Operator help pages can change before an editorial page is rebuilt. The checked date on this page indicates when the source set was reviewed, not a guarantee that a limit or timing will remain fixed. The live cashier, withdrawal confirmation and current Help Centre take priority.
Resolve the named cause first; a smaller amount will not fix an identity, method-ownership or blocked-account issue. Once the route is clear, use a single controlled transaction and wait for its stated result. If the result is uncertain, pause rather than increasing the amount or switching repeatedly between methods.
Payment check 08
Account rules that apply to every payment route
Payment availability is account-specific even when a method appears in the public help centre. The live cashier remains the decisive screen because it reflects the country, preferred currency, registered payment methods and any account control currently in force. A reader should stop if the live EUR account contradicts a dated guide; repeating a transaction is not a reliable way to solve an eligibility or authorisation problem.
Sky Betting & Gaming requires payment methods to belong to the named account holder. A partner’s card, a shared wallet or a bank account in another person’s name can trigger removal of the method, document requests or an account restriction. The practical check is simple: the personal details on the payment route should match the details used for the Sky account before any amount is entered.
New Republic of Ireland customers may have to complete identity and address verification before they can deposit, withdraw or play. Electronic checks can be enough, but manual review may require one accepted photo ID and two accepted Irish proof-of-address documents. Clear colour files, matching names and recent dates reduce avoidable back-and-forth; they do not guarantee an instant review.
The Net Deposits rule affects where money can be withdrawn. Deposits minus withdrawals are tracked for each registered route, and positive net deposits generally have to be returned to that route before extra funds can move elsewhere. This is why the fastest-looking withdrawal option is not always selectable. The withdrawal screen shows the relevant amount beside each method and should be read before submitting a request.
Keep a simple record of the attempt: method, EUR amount, date, time, on-screen status and any transaction reference. Do not publish or send a full card number, CVV, bank password or one-time code. If support asks for proof of card ownership, follow the secure instructions in the help centre and expose only the digits specifically requested there.
Promotion eligibility is a separate question from whether a deposit technically succeeds. Sky’s deposit guidance says a qualifying promotional deposit must be made by debit card or Apple Pay when the promotion requires a deposit. Pay by Bank can still be a supported funding method while not satisfying that particular promotional route. Always read the promotion attached to the account before choosing the payment method.
Troubleshooting
Common payment problems and the next useful action
| What you see | Likely explanation | Next action |
|---|---|---|
| Provider declined | The issuer denied authorisation | Ask the provider; it will not disclose its reason to Sky |
| Manual authorisation | Several online payments triggered a review | Contact support or the provider rather than repeating |
| Card will not add | Details, ownership or existing use are invalid | Correct the details or use an eligible owned method |
| Deposit control | The lowest active account limit is reached | Wait for reset or lower the planned spend |
| Account block | Sky attempted contact or restricted deposits | Use the support route shown in the account |
Documents and checks
Evidence to prepare without exposing credentials
Keep the date, time, EUR amount, payment method, on-screen status and any transaction reference. If account verification is requested, use only the secure upload route and the accepted document list. Never send a bank password, CVV or one-time security code.
Alternatives
Compare the supported route before switching
| Route | Deposit | Withdrawal | Fee position | Promotion note |
|---|---|---|---|---|
| Pay by Bank | Authenticate through the eligible bank | Different from card authorisation | Use only if shown in cashier | Not the promotional deposit route |
| Debit card | Issuer authorisation required | Check number, expiry and ownership | Up to three cards | Promotion-eligible when required |
| Apple Pay | Wallet and underlying card approval required | Device authentication can expire | No debit-card slot used | Promotion-eligible when required |
Quick answers
Frequently asked questions
Why was my deposit declined?
Usually because the provider denied authorisation; the on-screen message can identify another account cause.
Should I retry immediately?
Not until you know whether the first attempt failed, is pending or needs provider action.
Can Sky tell me why my bank declined?
The operator says providers do not share all refusal reasons, so you may need to ask the provider.
Can a deposit limit cause a decline?
Yes. The lowest active account control can block the amount.
Can I still withdraw?
A blocked deposit does not necessarily block withdrawals; check the separate Withdraw screen.